null
Freight forwarding, contract logistics, special transports: Mittelstand logistics providers are in the focus of international buyers. We advised Cologne-based MBS Logistics, with 26 locations and more than 450 employees, on its sale to AD Ports Group of Abu Dhabi.
International buyers discover the German Mittelstand
Logistics is Germany's third-largest economic sector after retail and automotive, and it is consolidating fast. Two patterns shape the market: foreign groups secure market access through established German Mittelstand companies, as AD Ports did with MBS Logistics, Nippon Express with Simon Hegele or Cosco with Konrad Zippel. And European networks such as Geis, Duvenbeck, Raben, Dachser or NTG Nordic are systematically acquiring forwarders. Unlike in other sectors, two thirds of buyers are strategic; financial investors build platforms mainly in specialist segments such as pharma, cold chain and chemical logistics.
For owners this means that a logistics provider with stable customer relationships, a clear specialisation and a functioning management team is today of interest to buyers from three continents. The difference in purchase price comes down to whether these buyers are actually at the table. That requires an internationally oriented process that approaches strategic buyers from Europe, the Middle East and Asia in parallel.
Freight forwarding and international networks
Air and sea freight, road transport, customs clearance, organised asset-light. Buyers are global networks and foreign groups acquiring trade lanes, customer relationships and customs expertise. International locations and a strong network in Asia or the USA are worth hard cash here.
Contract logistics and specialist segments
Pharma, cold chain, chemical and dangerous goods logistics, time-critical transport, heavy-lift and project logistics. Here financial investors build platforms and strategic buyers acquire specialists. Certifications, quality credentials and long-term customer contracts drive the price.
Regional transport and system logistics
Groupage, scheduled network traffic, food and building materials logistics with an own fleet. Buyers are European consolidators seeking network density and regional presence. Driver base, fleet condition and real estate determine the structure of the transaction.
What buyers pay for in this sector
Logistics companies are valued on sustainable EBITDA, freight forwarders additionally on gross profit. Three factors decide the multiple.
Asset-light or asset-heavy
An own fleet and own real estate tie up capital and depress the multiple, but increase the asset value. Real estate is often carved out before the sale and leased back. Asset-light forwarders with high gross profit per employee achieve the highest multiples.
Specialisation and certification
GDP for pharma, temperature control, dangerous goods, AEO customs status, IATA and aviation security approvals. Specialisation creates barriers to entry and pricing power and attracts buyers looking for precisely that capability.
Customers, contracts and team
Terms and concentration of customer contracts, share of contract logistics, driver and skilled labour base, as well as IT and digitalisation of processes. Buyers pay for predictability and a team that functions without the owner.
Market data: logistics service providers in the M&A market
Our semi-annual Industry Update summarises the market environment, transactions, active buyers and valuation level of the sector. The key figures of the July 2026 edition:
Active buyers are strategic consolidators such as DSV, Kuehne+Nagel, Dachser, Geis, Duvenbeck, Raben, NTG Nordic, AD Ports, Nippon Express and Cosco, as well as financial investors and platforms such as AUCTUS / Oxalis, GREENPEAK / VITAIRA, Castik / Customs Support, Orlando Capital, JLL Partners, SüdBG and Constellation Cold Logistics. Specialisation pays: pharma, temperature-controlled and chemical logistics attract most platform investors.
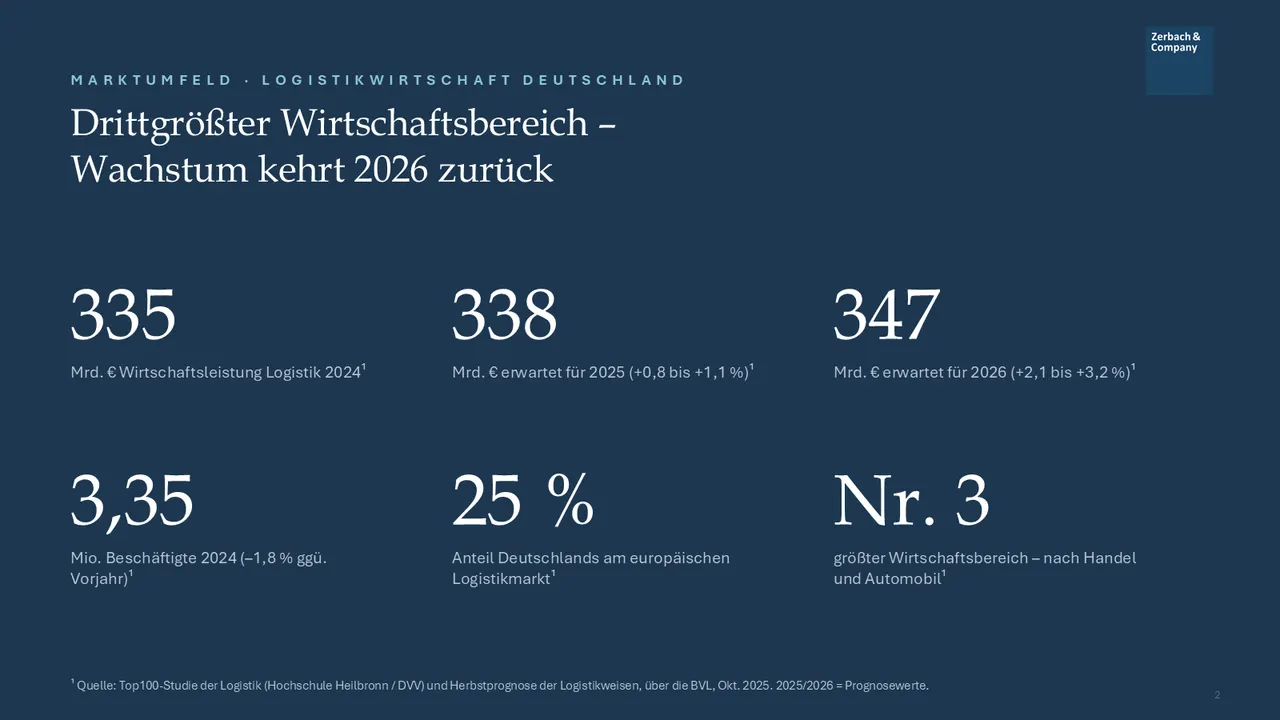
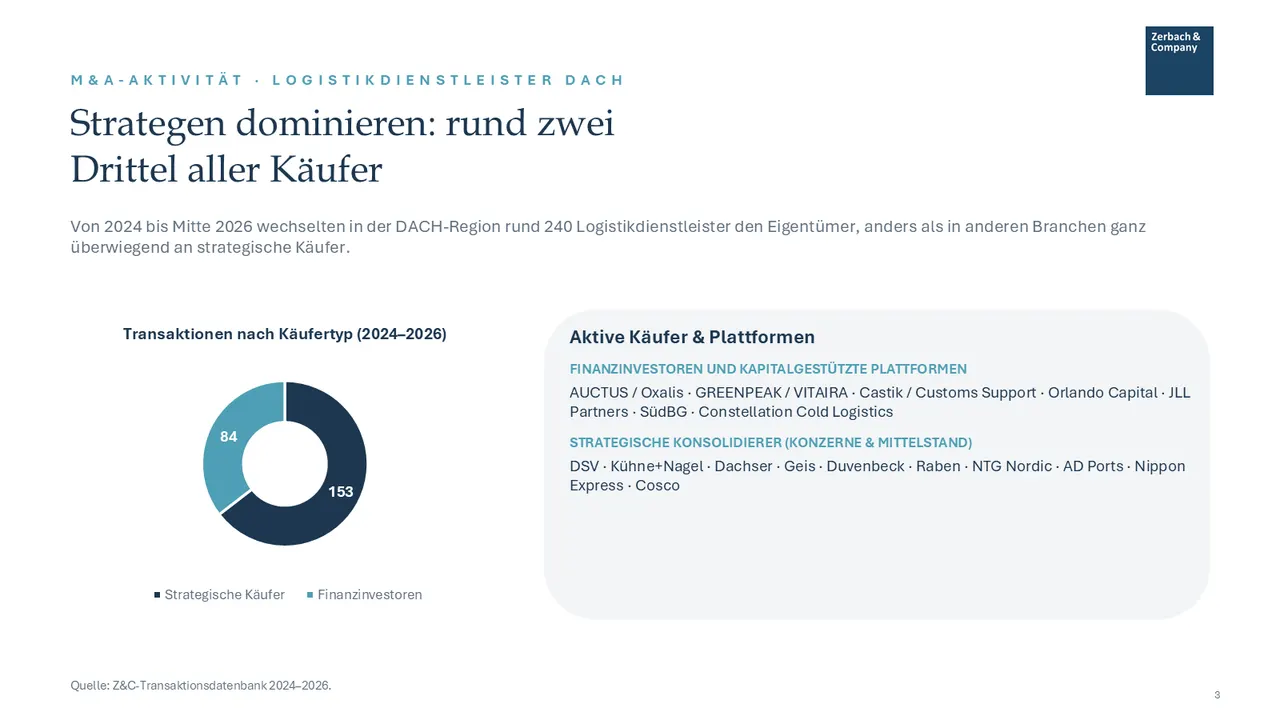
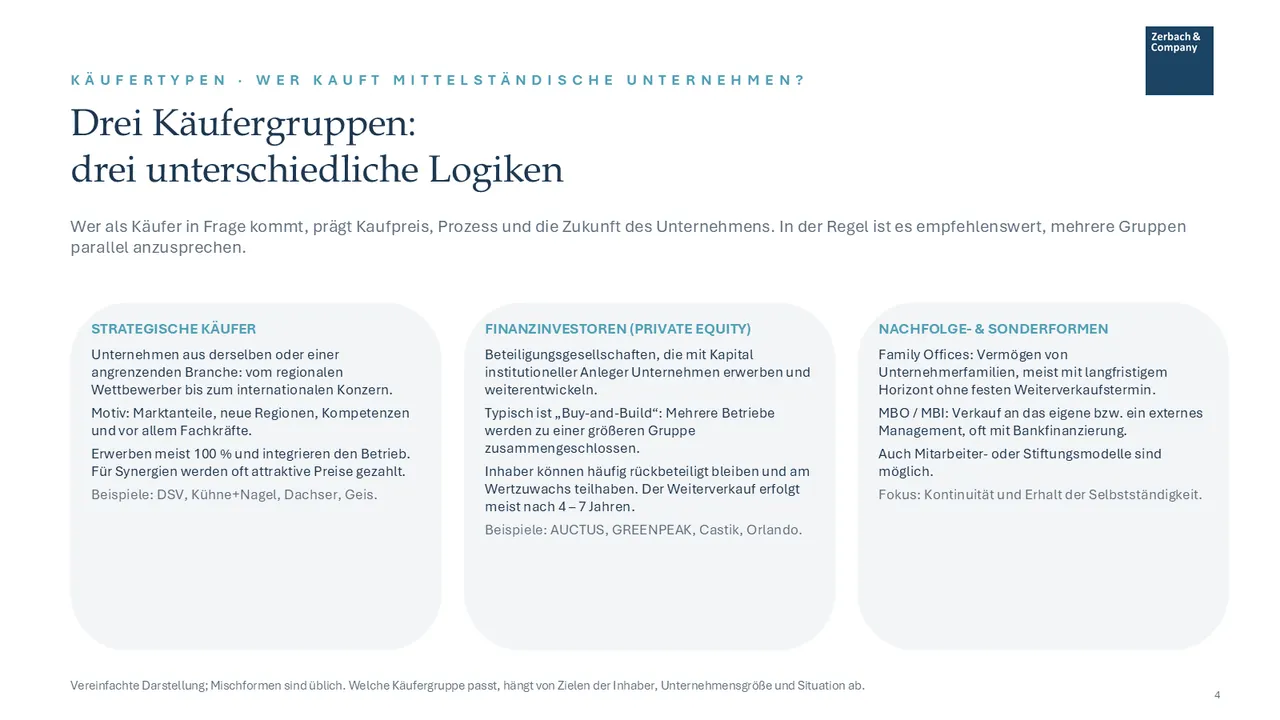
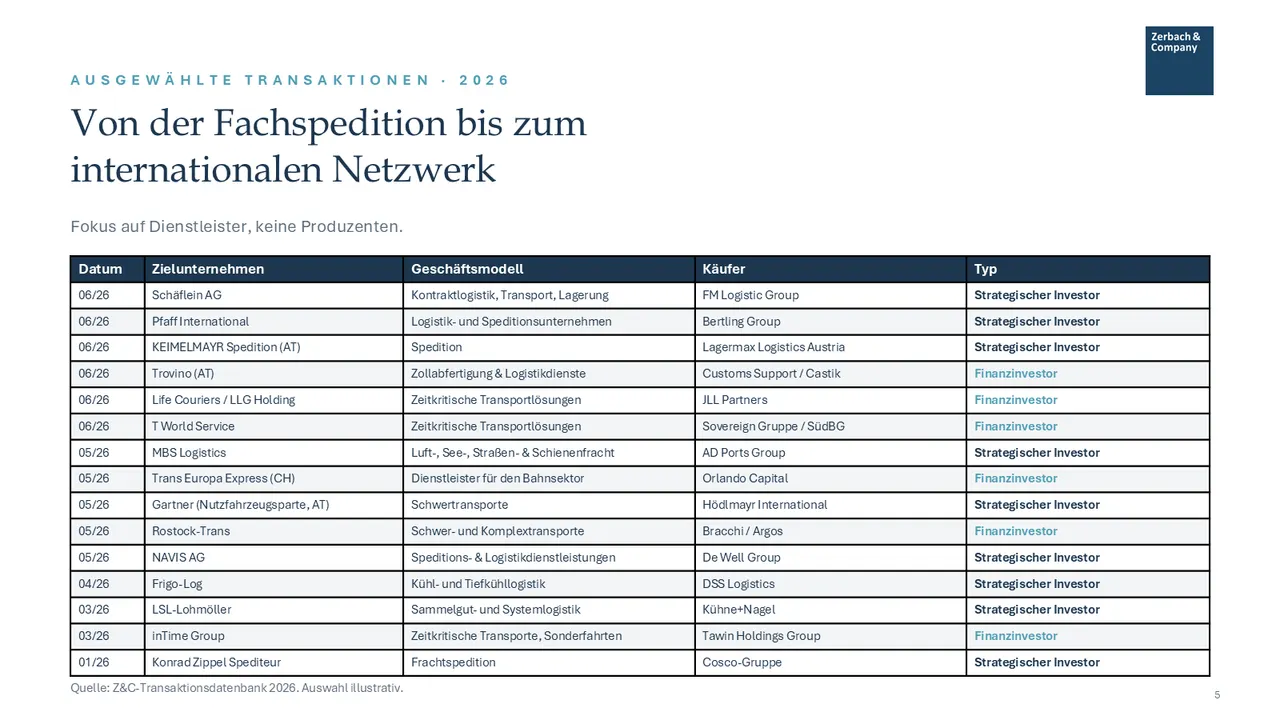
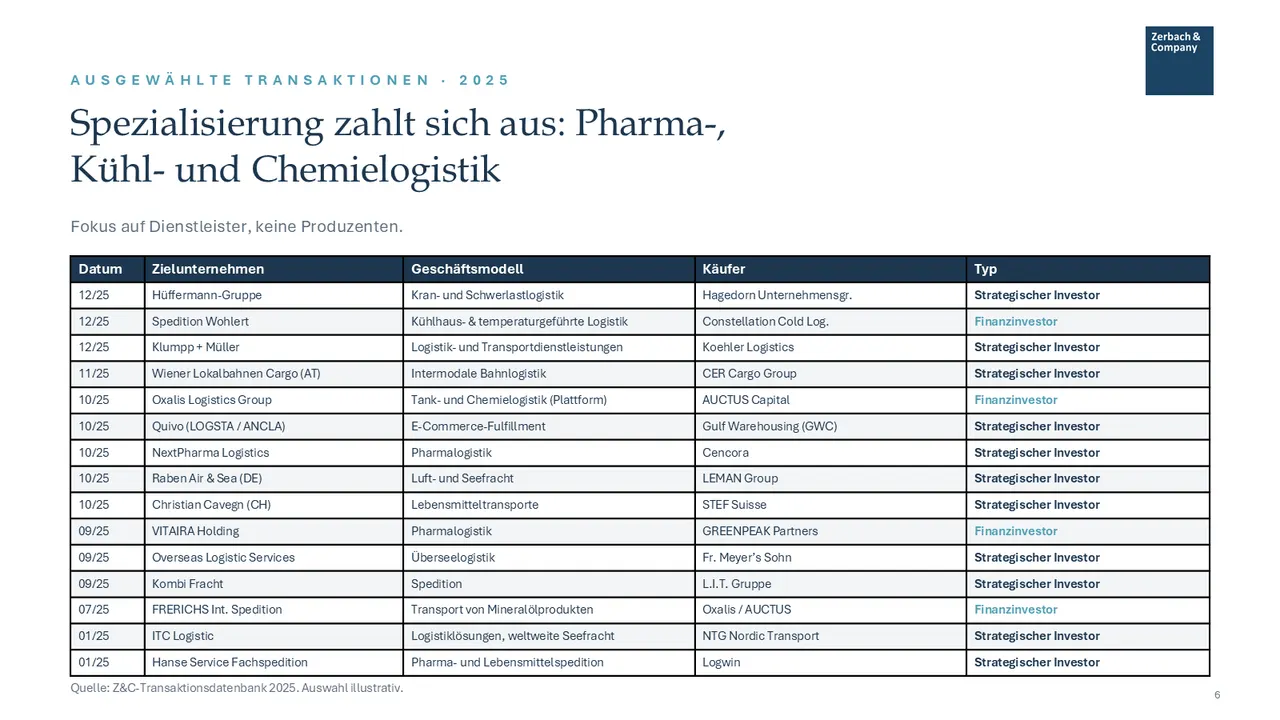
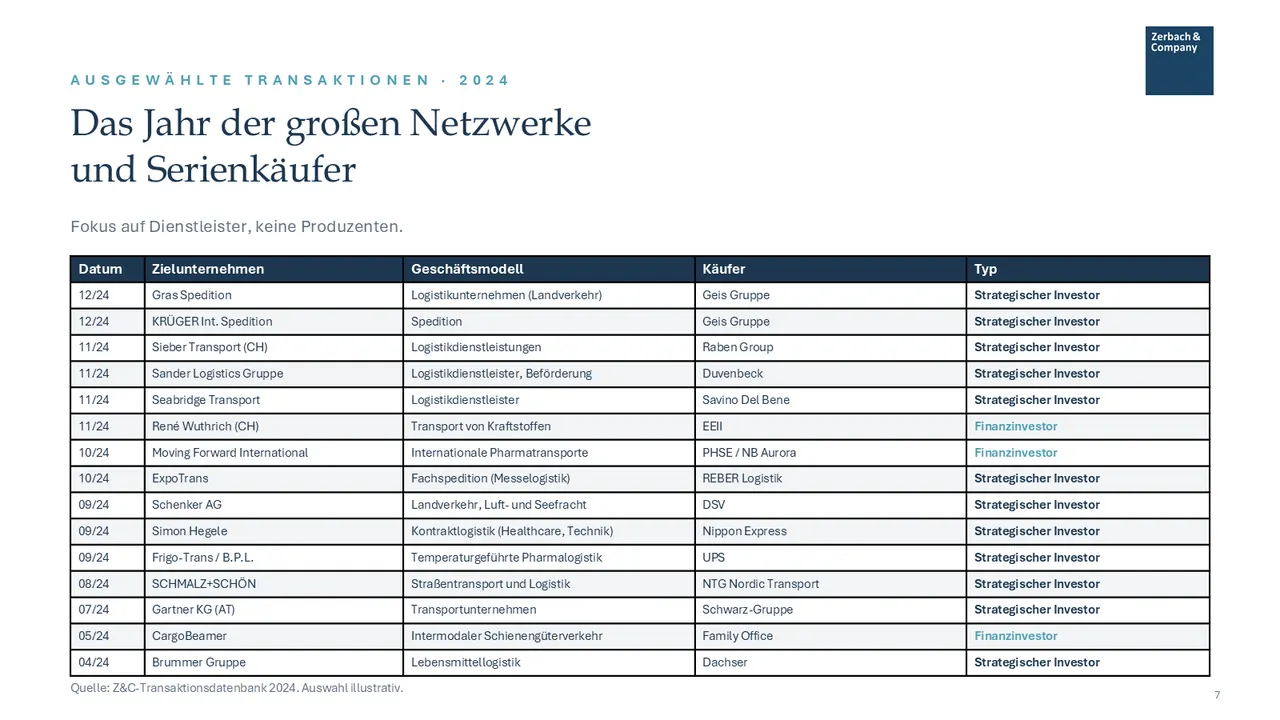
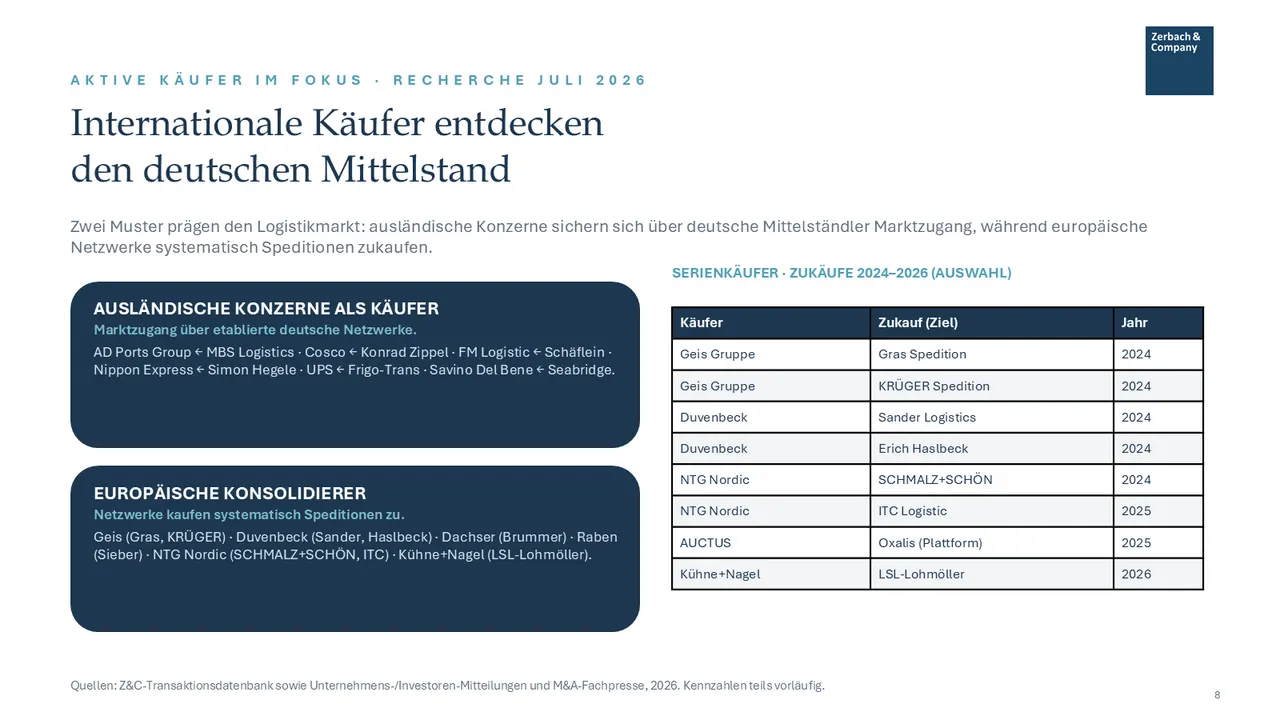
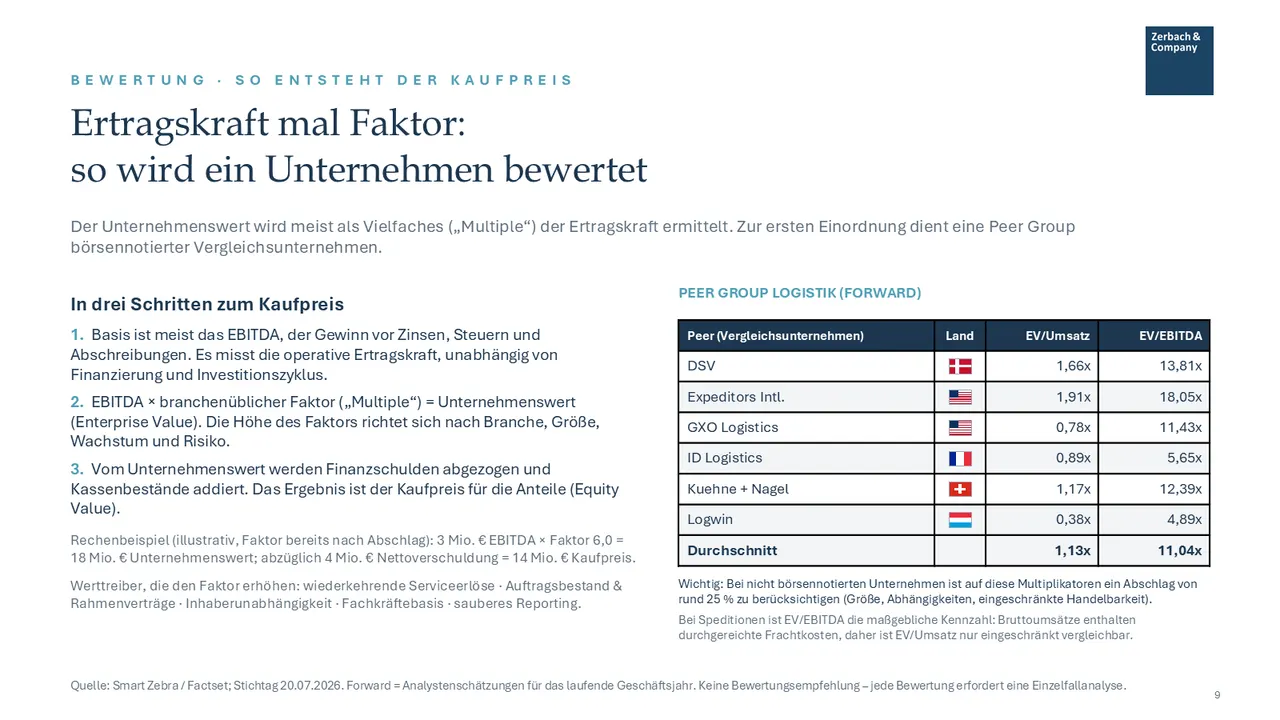
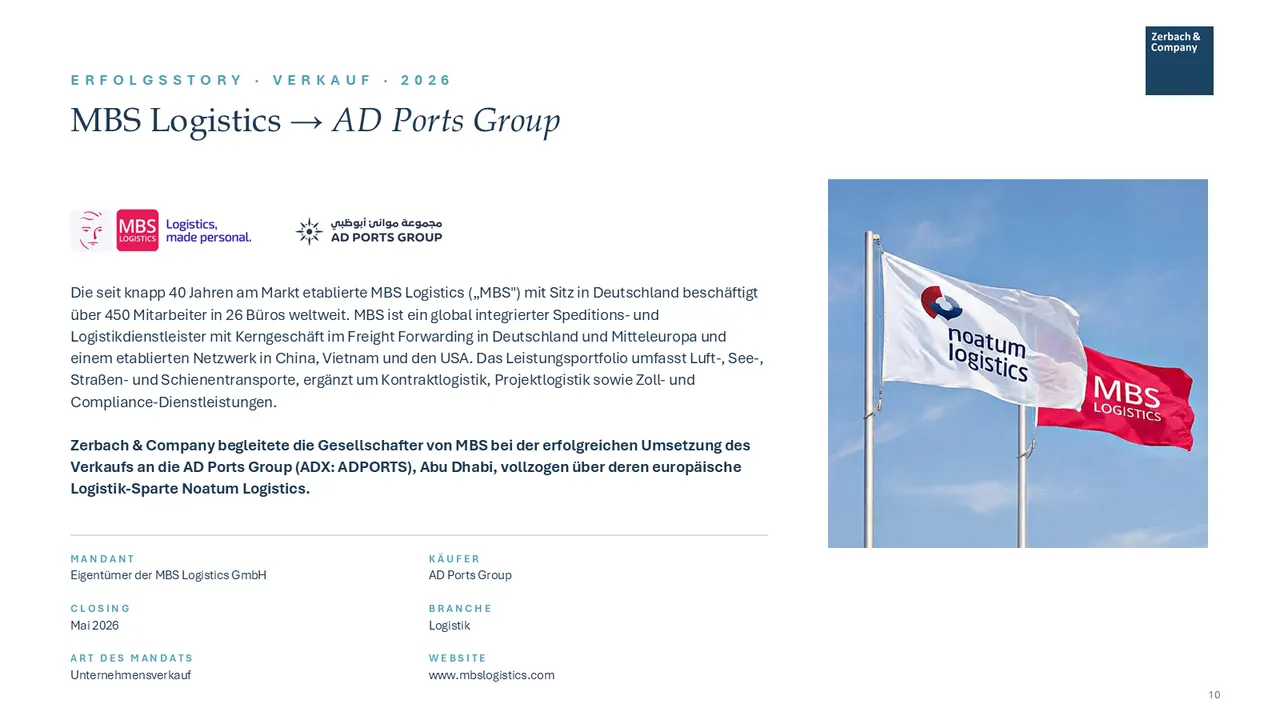
Scroll through the pages; a click opens the page in the PDF. As of July 2026, updated semi-annually. The report is in German.
MBS Logistics → AD Ports Group (Abu Dhabi)
Active for almost 40 years, Cologne-based MBS Logistics offers air, sea, road and rail freight, contract and project logistics and customs clearance from a single source, organised asset-light, with 26 locations worldwide and a strong network in China, Vietnam and the USA. The shareholders sold their shares to the listed AD Ports Group, for which MBS opens up access to the European market.
Read the full announcement →What MBS Logistics says about working with us
Throughout the entire process, Zerbach & Company proved to be a partner we could trust without reservation. Frank Eckertz and his team guided us through every phase with outstanding professional expertise, great diligence and a clear understanding of our entrepreneurial objectives. Even in demanding negotiation situations, Zerbach & Company acted with confidence, structure and a strong focus on solutions. We were particularly impressed by the combination of professionalism, reliability and genuine personal commitment. We felt excellently advised and supported at all times. We would therefore recommend Zerbach & Company without hesitation.
Questions on selling a logistics company
How is a forwarder or logistics provider valued?
The basis is sustainable EBITDA, for forwarders additionally gross profit, multiplied by a factor that reflects specialisation, customer structure and capital intensity. Listed networks set the upper end of the range; Mittelstand companies sit below it. Fleet and real estate are considered separately. Our fixed-price company valuation provides an initial assessment.
Are foreign buyers a realistic option for my company?
Very likely. Groups from the Middle East, Asia and the USA as well as European networks are deliberately acquiring German logistics providers to gain market access and trade lanes. The key is that these buyers are approached in the process; to that end we run processes in English and with international partner networks.
What happens to the fleet and the real estate?
That is a structural question we clarify early. Real estate is often transferred to a separate company before the sale and leased to the buyer, which secures you ongoing income and does not burden the purchase price for the operating business. As for the fleet, buyers examine age, financing and leasing contracts.
What becomes of drivers and employees?
In logistics, acquirers buy above all the team and the customer relationships, so continuity is in their interest. In a share sale, employment relationships transfer unchanged. Commitments on sites and employment can be anchored contractually; we make them a criterion in buyer selection.
How long does the sale take?
From preparation to signing, we expect six to nine months. With foreign buyers, time limits for foreign investment reviews or merger clearances may be added. Confidentiality towards customers, employees and competitors is maintained until signing.
Do you run a logistics company and are thinking about the future?
The first conversation is non-binding and, of course, confidential.